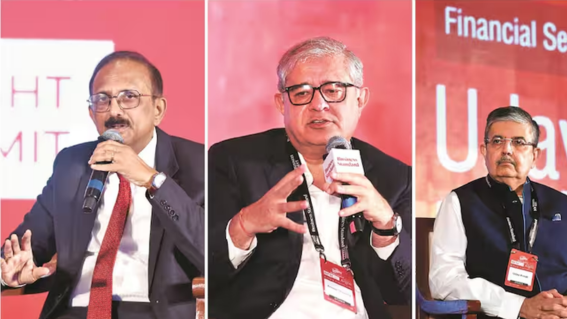
27 October 2026 (Navroze Bureau) Indian banks are preparing for a potentially higher interest-rate environment as rising funding costs, competition for deposits and expectations of further monetary tightening emerge as key challenges for the financial sector. Senior banking executives highlighted these concerns at the Business Standard BFSI Insight Summit 2026 in Mumbai, warning that higher rates could affect borrowing demand while lenders continue to navigate strong credit requirements.
State Bank of India (SBI) Chairman C S Setty said the bank’s internal outlook pointed to a possible cumulative interest-rate increase of 50 basis points by December. One basis point is one-hundredth of a percentage point, meaning a 50-basis-point increase would equal 0.50 percentage point.
The projection reflects SBI’s assessment of the interest-rate environment and should not be interpreted as a confirmed decision by the Reserve Bank of India (RBI). The central bank’s future policy decisions will depend on economic conditions, inflation and other relevant indicators.
Setty indicated that higher interest rates could moderate borrowing in rate-sensitive segments and affect discretionary consumption and consumer credit. However, he expressed confidence in the broader banking sector’s asset quality, citing India’s economic growth and continued demand for productive credit.
Rising funding costs pose a challenge
A major concern for lenders is the increasing cost of raising fresh deposits. Banks need stable funding to support loans to businesses, households and infrastructure projects, but deposit growth has struggled to keep pace with credit demand.
Amitabh Chaudhry, managing director and chief executive officer of Axis Bank, highlighted the pressure from tighter liquidity and rising incremental deposit rates. As banks compete to attract funds, they may have to offer more attractive rates to depositors, increasing their overall cost of funding.
Higher deposit costs can affect banks’ net interest margins, which measure the difference between interest earned on loans and investments and interest paid on deposits and other borrowings. The impact will depend on how quickly lending rates adjust compared with funding costs.
Infrastructure investment, working-capital requirements and the expansion of formal credit continue to support lending demand. Banks must therefore balance the need to finance economic activity with the challenge of maintaining profitability and adequate liquidity.
FCNR(B) deposits provide temporary relief
The summit also focused on the Reserve Bank of India’s special foreign currency non-resident (bank), or FCNR(B), deposit mobilisation scheme. The initiative helped Indian banks attract substantial overseas funds through a special dollar-rupee swap facility that reduced currency-hedging costs.
According to discussions at the summit, banks mobilised around $133 billion under the scheme between June and August. These inflows helped lenders manage funding pressures at a time when the credit-deposit ratio was elevated and competition for domestic deposits was intense.
However, the funds are not a permanent solution. Uday Kotak, founder and non-executive director of Kotak Mahindra Bank, estimated that repayments, including interest, could reach $160 billion to $170 billion over the next three to five years.
Kotak described the inflows as a temporary buffer against economic and geopolitical uncertainty and urged policymakers, banks and businesses to use the intervening period to strengthen the economy and prepare for the eventual repayment obligations.
The deposits can provide banks with additional liquidity and time to address the gap between loan growth and deposit mobilisation. Nevertheless, lenders will need to plan for the maturity of these liabilities and ensure that future funding requirements can be met without excessive pressure on costs.
Deposit mobilisation remains critical
Changing household savings patterns are adding to the challenge. SBI’s Setty noted that customers were moving money more readily between savings accounts, fixed deposits and other financial products.
This mobility makes it harder for banks to rely on traditional deposit relationships. Lenders increasingly need to offer competitive products and maintain customer confidence while managing the cost of attracting funds.
The impact of higher interest rates will not be uniform across all banks. Institutions with strong deposit franchises may be better positioned to manage funding expenses, while lenders more dependent on expensive wholesale funding could face greater pressure.
The timing of any increase in retail deposit rates will depend on credit demand, the movement of fresh deposits and the availability of other sources of funds. Bank executives indicated that the recent FCNR(B) inflows had eased some immediate pressure, although longer-term funding challenges remain.
Global uncertainty adds to the pressure
The discussions also highlighted the effect of global financial conditions on India’s banking sector. Elevated crude oil prices, changes in US bond yields and uneven foreign capital flows can affect the rupee, government bond yields and the cost of raising funds overseas.
Economists and treasury executives at the summit discussed the challenge of attracting foreign capital while reducing vulnerability to volatile international flows. Demand for artificial intelligence investments in developed markets has also influenced the allocation of global capital, adding to the uncertainty facing emerging economies.
Smaller non-banking financial companies (NBFCs) may face additional pressure because many rely on bank borrowing and market-based funding. Higher borrowing costs can be more difficult for lenders with lower credit ratings or limited access to alternative funding sources.
Technology and risk management in focus
Beyond interest rates, banking leaders stressed the importance of using technology more effectively. Executives called for banks to move beyond limited artificial intelligence pilot projects and towards wider deployment, supported by reliable data, strong cybersecurity and clear accountability.
As digital financial services expand, institutions must also manage operational risks, protect customer information and maintain robust internal controls.
The summit’s discussions indicate that banks face a combination of challenges: funding growth, managing interest-rate risk, preparing for future foreign currency repayments and investing in technology.
For the sector, the immediate priority is to maintain adequate liquidity and support credit demand without allowing funding costs to undermine profitability. The longer-term challenge will be to build more stable deposit bases and prepare for changing domestic and global financial conditions.